Credit Sesame: Grow your score

Screenshots
Details
- Rating
- 32.08K reviews
- Version
- 7.24.1
- Developer
- Credit Sesame, Inc.
Analysis by Norviv
Hey there, fellow finance enthusiasts! So, I recently got my hands on Credit Sesame, and let me tell you, it's a game changer for anyone who's looking to up their credit score game. If you've ever found yourself wondering how to grow your credit score without diving into a sea of financial jargon, this app might just be your new best friend. Let's dive into all the juicy details.
Start with a useful baseline, not a quick fix
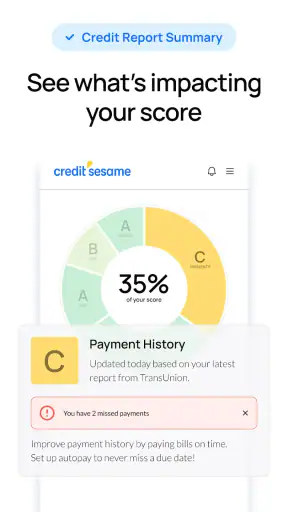
The first practical value of a credit app is giving you a place to begin. Before acting on a recommendation, I’d look at the score and report information together, then note what seems familiar and what deserves a closer check. A number alone can feel definitive, but credit decisions usually make more sense when you understand the account details and changes behind it.
For a realistic routine, imagine checking the app after paying bills on a Sunday evening. I’d make a note of the current picture, look for any new alerts, and choose one manageable action for the coming week, such as reviewing a balance or confirming that a payment was recorded as expected. That is more useful than opening a score tracker repeatedly and hoping for an immediate change.
Credit Sesame is a free finance app from Credit Sesame, Inc. Its average rating is 4.7 from around 196,000 ratings, and it has been installed over 5 million times. Those figures suggest it has reached a broad audience, but they don’t tell me whether its approach suits every borrower. I’d treat it as a practical companion for keeping an eye on credit, not as a promise that a score will rise on a particular schedule.
Getting Started with Credit Sesame
First things first, downloading Credit Sesame is a breeze. Available on both Android and iOS, it’s just a quick search away on your app store. Once you’ve got it installed, the signup process is pretty straightforward. You’ll need to provide some basic info, but nothing too invasive. I mean, they make it way easier than trying to decipher a bank statement!
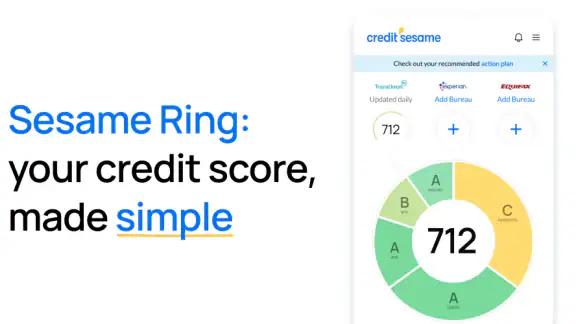
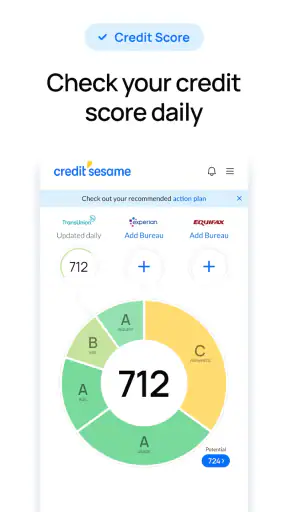
The app’s interface is super user-friendly. As soon as you log in, you’re greeted with your current credit score, which updates monthly. It’s like having a personal financial advisor tucked right in your pocket. And for those of us who like things visual, the app uses simple graphs and charts to show your credit progress over time. Trust me, you don’t need to be a math wiz to understand it.
Diving Into the Features
One of the standout features for me is the credit score simulator. Imagine being able to see how different financial decisions could impact your score before you actually make them. Thinking of opening a new credit card? The simulator can show you how that might play out. It’s like having a little crystal ball for your finances.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I’d use a simulator as a way to compare possibilities, not as a forecast to build a major decision around. For example, if you’re weighing whether to apply for a card, first consider why you need it, its costs, and whether you can manage another payment. Then use the estimate to think through the possible credit effect. A simulated result can make a trade-off easier to picture, but it cannot guarantee the outcome; actual reporting and individual circumstances matter.
Another cool feature is the personalized financial advice. Credit Sesame offers tailored recommendations on how to improve your credit score based on your current situation. It's not just generic advice; it's like having a financial coach who actually gets you.
My tip is to turn a recommendation into a small, verifiable task rather than treating it as a broad instruction. If the guidance points you toward checking an account, review the account details and compare them with your own records before changing anything. If it suggests a product, pause and assess the full terms and your budget. Recommendations can help organize your next question, but they should not replace your own review of a lender’s terms or a decision that depends on your wider finances.
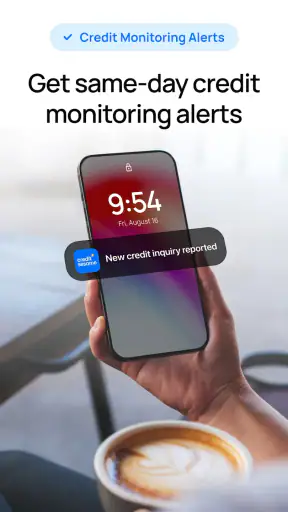
If that’s not enough, the app also keeps a close eye on your credit report and notifies you of any changes. Identity theft is no joke, so having that extra layer of monitoring is pretty reassuring. Plus, they offer free identity theft insurance, which is a nice little bonus.
Alerts are most useful when you decide in advance how you’ll respond to them. I’d check whether a reported change is something I recognize, confirm the details against relevant records, and follow up through the appropriate channel if it looks wrong. An alert is a prompt to investigate, not proof by itself that fraud has happened. Keeping that distinction in mind can help you act promptly without panicking over every notification.
Settings and habits that make monitoring manageable
Because credit updates are not the same thing as a live view of every financial event, I wouldn’t make a habit of checking the score several times a day. A repeatable review works better: open the app at a regular time, scan for changes, and give any unfamiliar item a careful second look. That keeps the app useful without letting normal fluctuations dictate your mood or spending choices.
I’d also make sure the contact details associated with an account are current, so important notices have a reasonable chance of reaching me. On a shared or frequently borrowed device, I’d be thoughtful about account access and avoid leaving financial information open for someone else to see. These are simple habits, but they matter more than chasing a setting that promises instant credit improvement.
Credit Sesame is rated for Everyone, and its current version is 7.24.1, with a minimum operating system requirement of 10. It has been available since June 28, 2012. I’d still check that my device meets the operating-system requirement before installing, particularly if I keep an older phone for day-to-day use. The app is free, so the main question is less about an upfront purchase and more about whether its monitoring and recommendations fit the way I want to manage credit.
Faster patterns for everyday decisions
A shortcut I find genuinely useful is to give each check-in a purpose. Instead of browsing without a plan, I’d decide whether I’m checking for a report change, reviewing my score trend, or thinking through a possible credit decision. That keeps the experience focused and makes it easier to remember what I learned the next time I open the app.
For instance, someone preparing to apply for an apartment might use a quiet moment to review their credit picture, look for unfamiliar changes, and make a list of questions to resolve before an application. Someone planning a large purchase could use the simulator to consider a possible action, then step away and compare that estimate with their budget and the actual terms available. In both cases, the app helps structure preparation; it does not decide whether an application or purchase is affordable.
Another helpful habit is keeping a private note of when you checked and what follow-up you chose, without copying sensitive account information into an unsecured place. A brief reminder such as “verify this account” or “review recommendation next week” can prevent a useful alert from disappearing into a busy day. I would avoid treating a single score reading as a progress report; trends and confirmed report details are more meaningful than reacting to every small movement.
How It Stands Out
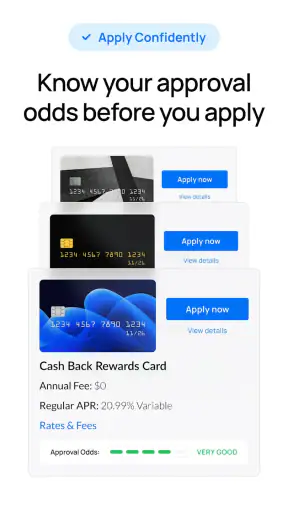
Now, I’ve tried a few credit tracking apps before, and what sets Credit Sesame apart is its holistic approach. It’s not just about monitoring your score; it’s about actively helping you improve it. They even offer access to better credit card offers and personal loans that can help you manage your finances more effectively.
This combination is convenient, but it also calls for a little discipline. A suggested card or loan is still a financial product, not automatically the right answer to a credit problem. I’d compare the full terms, consider whether the payment fits my budget, and decide whether I need the product at all before pursuing an offer. If my main goal is simply to understand a report, a credit bureau’s own tools or a service focused only on monitoring may feel less distracting. If I want monitoring alongside guidance and offers in one place, Credit Sesame has a more bundled approach.
Compared with checking a score through a bank or card issuer, a dedicated app can be appealing because it puts credit monitoring and related advice in a single routine. The trade-off is that I would not assume two services show identical scores or update at the same time. When preparing for a lender’s decision, I’d follow the lender’s instructions and rely on the information it actually uses rather than expecting any one consumer app to predict the result.
Another thing I really appreciate is the educational content. The app provides a bunch of articles and tips on credit management that are super easy to digest. Whether you’re a credit newbie or a seasoned pro, there’s always something new to learn.
For a newcomer, that kind of material can make credit language less intimidating and help turn a vague goal into a sensible next step. For someone experienced, it may be most valuable as a quick refresher rather than a substitute for detailed research. I’d use it to identify what I need to understand, then seek more specific guidance when a decision involves complex debt, a disputed item, or terms I’m not comfortable interpreting.
Where the app helps, and where I’d choose another route
I think the app is a good fit for someone who wants a simple recurring view of credit and appreciates having alerts, learning material, and personalized suggestions nearby. It can also suit a person who is just beginning to build credit and needs an approachable way to become familiar with the subject. The strongest use case is steady awareness: checking in, noticing a change, and following up thoughtfully.
I’d be less enthusiastic about using it as the only source of truth for a time-sensitive loan, mortgage, or rental decision. A consumer-facing score display is useful for orientation, but lenders can apply their own criteria and may consider information in ways the app cannot represent. If a report item is seriously disputed, or a financial choice has legal or major budget consequences, I’d go directly to the relevant reporting agency, lender, or qualified adviser rather than expecting an app recommendation to resolve it.
It may also be a poor match for someone who would rather avoid product recommendations or who finds frequent financial notifications stressful. In that case, a simpler bureau or bank-provided monitoring option may be more comfortable, even if it offers less guidance in one place. The best tool is the one you can use calmly and consistently, not the one with the most prompts.
Advanced limits and a sensible way to use the advice
The simulator and tailored suggestions are useful for planning, but I’d keep their role modest. They can help me frame a question—what might happen if I make this change?—without turning an estimate into a promise. Credit outcomes depend on a person’s wider history and on how accounts are handled and reported. That means a simulated scenario is a comparison aid, not a substitute for checking the real costs and consequences of a decision.
Likewise, monitoring can help surface changes, but it cannot make every issue disappear on its own. I would still need to verify an unfamiliar entry, contact the right organization, and keep track of any follow-up. The identity theft insurance mentioned in the app is reassuring as an added benefit, but I’d read the applicable terms and understand what it covers rather than assuming it replaces careful account security or the work of responding to suspected misuse.
The same measured approach applies to score movement. I would not open a new account simply because I want a faster change, nor would I make a payment decision based on a graph alone. Instead, I’d use the app to stay informed, focus on actions I can verify, and give routine financial habits time to matter. That is a less exciting strategy than chasing a quick jump, but it is much more sensible.
Final Thoughts
All in all, Credit Sesame is a fantastic tool for anyone serious about improving their credit score. It’s packed with features that are not only useful but also incredibly easy to use. Whether you’re trying to boost your score to buy a house, get a new car, or just want to see that number go up, this app is worth checking out.
My recommendation is to treat it as a credit dashboard and learning aid, not a financial decision-maker. Set a steady check-in habit, use alerts as prompts to verify changes, and consider offers only after comparing their real terms with your needs. That routine makes the app more valuable than repeatedly refreshing a score and hoping for a quick result.
So, if you're ready to take control of your financial future and watch that credit score grow, give Credit Sesame a try. It might just be the financial wingman you’ve been looking for!
Frequently Asked Questions
01What is Credit Sesame and how does it help improve my credit score?
Credit Sesame is a financial app designed to help users manage their credit scores and overall financial health. It provides free access to your credit score, credit monitoring, and personalized advice to improve your score. The app's features include credit card and loan recommendations tailored to your credit profile, which can help you make informed financial decisions.
02Is Credit Sesame free to use, and are there any hidden charges?
Credit Sesame offers a free version that includes credit score tracking, credit monitoring, and financial tips. While the basic features are free, there are optional premium services available for a fee, such as identity theft protection and advanced credit monitoring. Users can choose to upgrade if they find these additional services beneficial.
03How secure is my personal information on Credit Sesame?
Credit Sesame takes user privacy and data security seriously, employing bank-level encryption and security protocols to protect your personal information. The app does not store your bank login credentials, and all data transfers are encrypted. Users can trust that their information is safeguarded against unauthorized access.
04How often is my credit score updated on Credit Sesame?
Credit Sesame updates your credit score once a month. This monthly update allows users to track changes over time and understand the impact of their financial decisions on their credit health. Regular updates help users stay informed and take timely actions to improve their credit scores.
05Can I use Credit Sesame outside the United States?
Currently, Credit Sesame is primarily available to users within the United States, as it relies on U.S. credit reporting agencies for its data. Users residing outside the U.S. may not have access to the app's full features, and some services may not be applicable in international markets.


